 By

Anticipation is mounting for the upcoming Anthropic and OpenAI IPOs. As a result, investor interest in companies that build and maintain the ever-expanding AI models has surged to an all-time high.
RELATED: AI companies constitute nearly half of S&P 500 market Cap in July 2024
But beyond the frontier AI companies lies a vast network of firms that have found a place within the wider AI economy. To identify how deeply AI has penetrated the U.S. economy, BestBrokers has released a recent report examining the largest stock market index, the S&P 500, and its constituents’ growing exposure to AI.
The team at BestBrokers analysed all 503 constituents of the S&P 500 and categorised companies according to their role in the AI economy, from chips and cloud providers to infrastructure, energy, security and businesses adopting AI.
They then calculated each category’s combined market capitalisation and weight in the index, using market-cap data as of July 2026. The full data used for this analysis can be accessed on Google Drive via this link
AI’s Mainstream Moment: 64% of S&P 500 Companies Leverage Artificial Intelligence
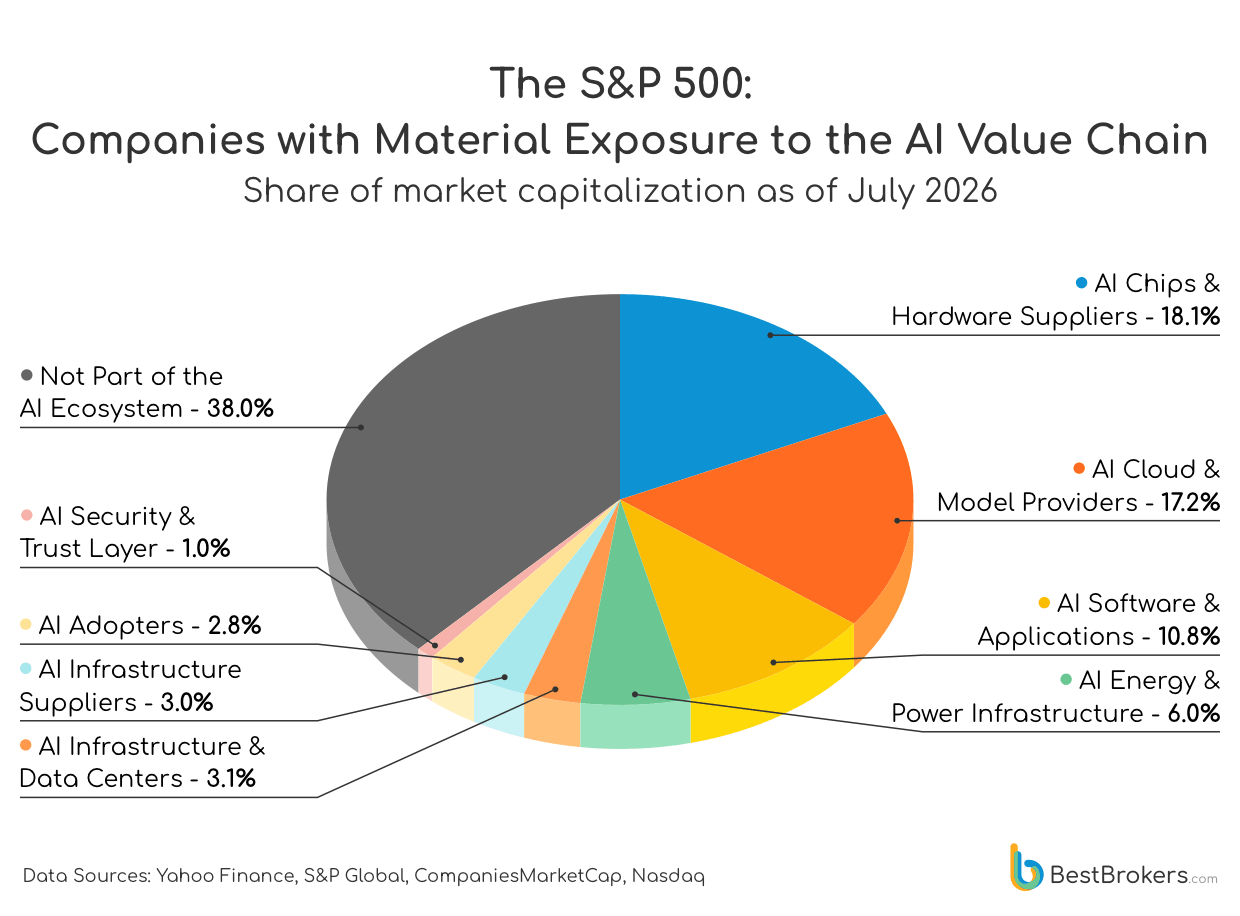
The analysis finds that companies with material exposure to the AI value chain now account for 62.04% of the S&P 500’s total market capitalisation.
From a niche technology theme just a couple of years ago, AI has become a market-wide investment story – more than three-fifths of the index’s value is now tied to companies that play a material role in the AI ecosystem, while only 37.96% sits outside it.
Key takeaways from the report
- The analysis shows that 62.04% of the S&P 500’s market value is represented by companies with material exposure to the AI value chain. These are 218 companies across eight different categories with a combined market capitalisation of around $42.4 trillion, meaning AI-related businesses now represent nearly two-thirds of the index by value.
- Among those 218 companies, AI Chips & Hardware Suppliers have the largest weight (18.14%). A total of 28 firms, including notable players like NVIDIA, Broadcom, Micron Technology, AMD, and Intel, are collectively worth $12.39 trillion.
- AI Cloud & Model Providers represent another 17.18%, worth $11.74 trillion – despite consisting of just five companies. Representing almost a fifth of the S&P 500, these are Microsoft, Oracle, Meta Platforms, Amazon, and Alphabet – the so-called hyperscalers.
- AI software is another $7.39 trillion market – the 17 companies under the AI Software & Applications category account for 10.82% of the S&P 500. While these companies (including Apple, Tesla, Palantir, and IBM) may receive much of the attention when it comes to real-world AI applications, their combined market value is still considerably smaller than the hardware and cloud segments.
- Another 7 companies making up the Security & Trust layer of the AI value chain have $674.5 billion in combined market value. These firms account for roughly 1% of the index and among them are Palo Alto Networks, CrowdStrike, and Fortinet.
More takeaways from the report
- AI infrastructure extends well beyond the obvious tech names, with 58 energy and utilities companies accounting for 6.01% of the total index weight. Data centres and infrastructure companies contribute another 3.14%, while 37 AI infrastructure suppliers account for 2.99%. Together, these less-visible parts of the AI supply chain represent roughly $8.3 trillion in market capitalisation.
- Nearly 38% of the S&P 500 remains outside the AI ecosystem – the report identifies 285 companies, representing 37.96% of the index, that do not have material exposure to the AI value chain under this methodology. That leaves a sizeable part of the market outside the AI trade, despite the technology’s growing influence on valuations and investor sentiment.
Growth highlights a potential concentration risk
‘AI’s influence on the stock market has grown far beyond the handful of companies most commonly associated with the technology. Our analysis shows that companies with material exposure to the AI value chain now represent 62.04% of the S&P 500 by market capitalisation, meaning investors are increasingly exposed to AI even without directly targeting it. The striking part is how much of this value sits outside AI software itself, with chips, cloud providers and supporting infrastructure accounting for much of the market’s AI exposure. This also highlights a potential concentration risk: a relatively small number of companies have an enormous influence on the index and, consequently, on investors’ portfolios. AI may still be a transformative technology story, but it has already become a defining stock-market story.’
– comments Alan Goldberg, data analyst at BestBrokers.
You can find a full breakdown of the companies building AI infrastructure, the fastest-growing AI stocks over the past two years, and how artificial intelligence has expanded from a niche technology theme into the dominant investment ecosystem within the S&P 500 in the full report.